The Rule of 72: How Long Until Your Money Doubles?
Divide 72 by the growth rate to get the years to double. How the rule of 72 works, how accurate it is, why it’s 72, and how to use it on debt and inflation.
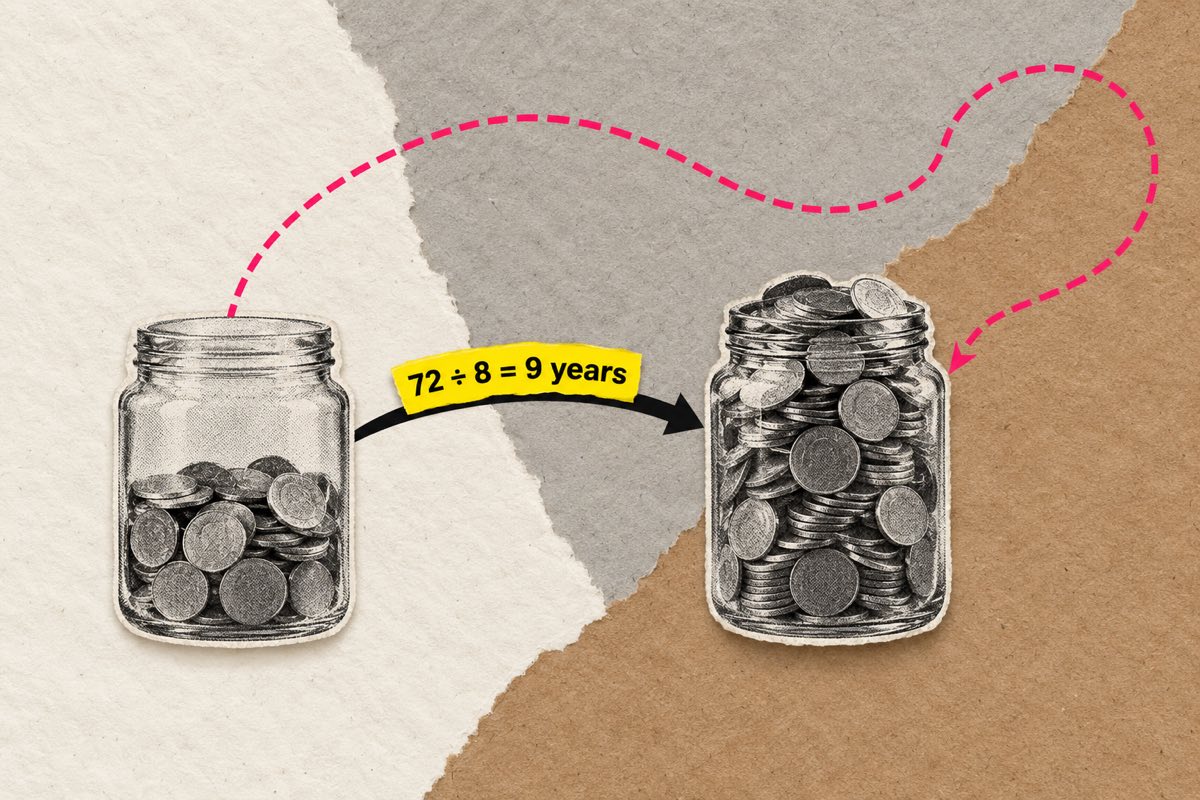
Suppose your savings grow at 6% a year. How long until they double?
You could reach for a calculator and work out how many times you need to multiply by 1.06 to reach 2. Or you could divide 72 by 6 and get 12. The real answer is 11.9 years. That trick is the rule of 72, and it’s one of the most useful pieces of mental arithmetic you can know, because it turns abstract percentages into something you can feel: years.
Try it
How long until it doubles?
Pick a yearly rate. Each step is one doubling, over fifty years.
At 7% a year, money doubles every 10.2 years. The rule of 72 says 72 ÷ 7 = 10.3, close enough to do in your head. Over 50 years that’s 4 doublings: 16 times what you started with.
The rule
Years to double ≈ 72 ÷ the yearly growth rate (as a percentage)
- At 3% a year: 72 ÷ 3 = about 24 years.
- At 6%: about 12 years.
- At 8%: about 9 years.
- At 12%: about 6 years.
It works in reverse too. If you want money to double in 10 years, you need about 72 ÷ 10 = 7.2% a year. If prices have doubled in 18 years, inflation has averaged about 4%.
The toy at the top shows it on a chart: pick a rate, and watch the doublings stack up over fifty years against the rule’s prediction.
How accurate is it?
Very, for everyday rates.
Try it
How good is the shortcut?
Pick a growth rate. Compare what the rule of 72 says with the exact doubling time.
At 8% a year, the rule says 9.00 years and the exact answer is 9.01: off by just 0.01 years. For everyday rates, it’s as good as a calculator.
The exact doubling time at 8% is 9.01 years; the rule says 9. At 6%, the exact answer is 11.9 years; the rule says 12. At 10%, 7.27 against 7.2. In the range most savings, investments and loans live in, roughly 4% to 12%, the rule is accurate to within a few months.
It drifts at the edges. At 1% it says 72 years when the truth is about 70. At 24% it says 3 years when the truth is about 3.2. At 50% it says 1.4 years against an exact 1.7. Even there, it’s good enough for a quick sense of scale, which is what it’s for.
Why does it work?
You can skip this section and the rule still works, but it’s satisfying to see why.
The exact doubling time is the natural logarithm of 2, about 0.693, divided by the natural logarithm of one plus the rate. For small rates, the logarithm of one plus the rate is very close to the rate itself, so the doubling time is close to 69.3 divided by the rate in per cent. That’s the “rule of 69.3”, which is exact for interest compounded continuously.
So why 72? Two reasons. First, at the rates people actually meet, 6% to 10%, the approximation slightly underestimates the doubling time, and bumping the constant up to 72 corrects for it. Second, 72 is wonderfully easy to divide: by 2, 3, 4, 6, 8, 9 and 12. Nobody wants to divide 69.3 by 7 in their head.
It’s an old trick. The Italian mathematician Luca Pacioli mentioned it in 1494 in a textbook for merchants, without explaining it, as though his readers already knew it.
Using it on debt
The rule works just as well against you. A credit card charging 24% a year doubles an unpaid balance in about 72 ÷ 24 = 3 years. Leave $2,000 untouched for six years and it grows to around $7,000: close to two doublings. That’s a vivid way to see why high-interest debt is so dangerous, and why paying it off is usually a better use of spare money than saving at a much lower rate.
For short-term loans priced by the month or the day, the rule is even more alarming. A loan at 3% a month, about 36% a year before compounding, doubles in about two years. A charge of 1% a day doubles a debt in about ten weeks.
Using it on inflation
At 3% inflation, prices double in about 24 years. Anything you save has to grow faster than that just to hold its value. At 6% inflation, prices double in 12 years, so money kept as cash for twelve years buys half as much. At 10% inflation, it takes just over seven years. There’s more on what that does to savings in inflation explained.
Using it on fees
Fees work like negative growth. A fund charging 2% a year more than a cheaper one takes a fee that, compounded, would double in about 36 years. Over a long career, that’s a large share of everything the money earns. The rule turns a small-sounding percentage into a timescale, and timescales are much easier to care about.
Doublings add up fast
Because each doubling builds on the last, they stack quickly: two doublings make 4 times, three make 8, four make 16, five make 32. At 7% a year, money doubles roughly every 10 years, so in 40 years it grows about 16-fold.
Try it
Think in doublings
A country’s economy grows at 7% a year for 40 years. Roughly how much bigger is it at the end?
Pick one. You’ll see why straight after.
This is the best reason to learn the rule. It turns long-run growth from something mysterious into a simple count. Ask “how many doublings is that?” and decades of compounding become a handful of steps.
| Yearly rate | Doubling time | Growth over 40 years |
|---|---|---|
| 2% | about 36 years | about 2.2 times |
| 4% | about 18 years | about 4.8 times |
| 7% | about 10 years | about 15 times |
| 10% | about 7 years | about 45 times |
The difference between 4% and 7% looks small as a percentage. Over forty years it’s the difference between multiplying your money by five and by fifteen.
Beyond money
The rule works on anything that grows by a steady percentage.
- Economies. When China’s economy grew at around 10% a year for three decades, it was doubling roughly every seven years. A country growing at 2% doubles in 36.
- Populations. A population growing 2% a year doubles in about 36 years; at 3%, in 24.
- Technology. Moore’s law, the observation that computer chips doubled in transistor count about every two years, implies growth of roughly 41% a year. The rule of 72 would say 1.75 years, a reminder that it drifts at high rates.
- Epidemics. In the early days of an outbreak, a disease growing 35% a day doubles in about two days. That’s why early action matters so much.
Practise it in your head
Three quick ones, with answers after each.
A savings account pays 4%. How long to double? 72 ÷ 4 = 18 years. And to quadruple? Two doublings: about 36 years.
House prices in a city doubled in 12 years. What was the average yearly rise? 72 ÷ 12 = 6% a year.
A salary rises 3% a year, and prices rise 3% a year. How long until the salary doubles? About 24 years. How long until it buys twice as much? Never, at those rates: the pay and the prices double together, so the real salary stands still. That last one is the most useful of the three, because it’s the one that headlines about pay rises tend to skip.
Cousins of the rule
There are matching rules for other multiples. Divide about 114 by the rate for the years to triple, and about 144 for the years to quadruple, which is just two doublings. At 8%, money triples in about 14 years and quadruples in about 18.
The limits
The rule assumes a steady rate. Real investments go up and down, and their returns aren’t promised. A stock market that has averaged 7% over a century can lose a third of its value in a year. So treat any doubling time for investments as an illustration of the maths, not a forecast. (General education, not advice for your own money.)
It also assumes growth compounds. Simple interest, paid only on the starting amount, doesn’t double in 72 ÷ rate years; at 6% simple interest, doubling takes a full 16.7 years.
Within those limits, it’s one of the most useful numbers to carry in your head. If you’d like to see compounding in more detail, compound interest explained has a chart of it, and the free money test starts with exactly this question.
Questions people ask
- What is the rule of 72?
- A quick way to estimate how long something takes to double at a steady growth rate: divide 72 by the rate in per cent. At 8% a year, 72 ÷ 8 is 9, and the exact doubling time is 9.01 years. It’s been used by bankers and merchants for at least five centuries.
- Why is it 72 and not 70?
- The mathematically exact constant for small rates is about 69.3, the natural logarithm of 2 times 100. But at typical rates of 6% to 10%, 72 fits slightly better, and it divides neatly by 2, 3, 4, 6, 8, 9 and 12, which makes mental arithmetic easy. Some people use 70 or 69 for low rates.
- How accurate is the rule of 72?
- Very accurate between about 4% and 12%, usually within a few months. At 1% it says 72 years against an exact 70; at 24% it says 3 years against an exact 3.2; at 50% it says 1.4 years against an exact 1.7. Beyond that it drifts, but it stays in the right neighbourhood.
- Can I use the rule of 72 for debt?
- Yes, and it’s a sobering use. A credit card charging 24% a year doubles an unpaid balance in about 3 years. A payday-style loan at 1% a day, around 365% a year before compounding, doubles in a matter of weeks.
- Is there a rule for tripling?
- Yes: divide about 114 by the rate to estimate the years to triple, and about 144 to quadruple, which is the same as two doublings. At 8% a year, money triples in roughly 14 years and quadruples in about 18.
Sources and further reading
- Pacioli, L. (1494). Summa de arithmetica, geometria, proportioni et proportionalità. Venice.
- Slavin, S. (1989). All the Math You’ll Ever Need. Wiley. (On rules of thumb for doubling.)
- US Securities and Exchange Commission, Investor.gov. The rule of 72.
- Financial Conduct Authority. MoneyHelper: Understanding interest rates and compounding.