Inflation Explained: What It Is and What It Does to Your Money
What inflation is, how it’s measured, what causes it, why central banks aim for 2% and not zero, and how it quietly shrinks savings and pay rises.
In 1923, at the worst point of Germany’s hyperinflation, prices were doubling every few days. Workers were paid twice a day and ran to the shops before their wages lost value. A dollar, which had bought about four marks before the First World War, bought over four trillion. Photographs from the time show children playing with bundles of worthless banknotes as building blocks.
That’s inflation at its most extreme. The everyday kind is far gentler, a few per cent a year, and so quiet that most people barely notice it until they look at what something cost ten years ago. But it does the same thing, just slowly: it makes money buy less.
Try it
What does $100 buy later?
Set the inflation rate and how many years pass.
At 3% inflation for 24 years, a basket that costs $100 today costs $203. Kept as cash, your $100 buys only 49% of that basket.
What inflation is
Inflation is a general rise in prices across an economy over time. When inflation is 3% a year, the same basket of things that cost $100 last year costs about $103 today.
The flip side is that each unit of money buys less. Inflation is really a fall in money’s purchasing power. Move the sliders in the toy at the top and you’ll see a basket of shopping grow more expensive, year by year, until today’s $100 buys only half as much.
The key word is general. If bananas get expensive because of a bad harvest, that’s a price change. Inflation is when prices across the board are rising.
How it’s measured
Statistics agencies track the prices of a large “basket” of goods and services that typical households buy: food, rent, energy, transport, clothing, haircuts, streaming services and so on. Each item is weighted by how much of a typical budget it takes, and the overall rise in the basket’s cost is the inflation rate. In the UK this is the Consumer Prices Index, compiled by the Office for National Statistics; in the US, the Bureau of Labor Statistics produces the CPI. The basket is updated every year, so it keeps up with what people actually buy: in recent years, things like air fryers have been added, and others dropped.
Your personal inflation rate can differ. If more of your money goes on things whose prices are rising fastest, such as rent, energy or food, inflation can feel much worse than the headline figure. That’s why poorer households often feel an inflation spike harder: a bigger share of their budget goes on essentials.
There’s also a sly version: shrinkflation, where the price stays the same but the packet gets smaller. Official measures try to adjust for it, but shoppers notice it before the statistics do.
What causes it
Economists group the causes into a few kinds, and real episodes usually mix them:
- Too much demand. When people and businesses want to buy more than the economy can produce, sellers raise prices. This is often called demand-pull inflation.
- Rising costs. When the cost of making things goes up, for example because energy prices jump, businesses pass it on. This is cost-push inflation.
- Expectations. If everyone expects prices to rise, workers ask for higher wages and firms raise prices in advance, which can make inflation stick.
- Too much money. If the amount of money grows much faster than the amount of goods and services, more money ends up chasing the same stuff. In extreme cases, when a government prints money to pay its bills, this is how hyperinflation happens, as in Germany in 1923 or Zimbabwe in 2008, where at its peak prices were doubling roughly every day and the government issued a 100-trillion-dollar note.
The surge of 2021 to 2023 is a good example of a mix. As economies reopened after the pandemic, demand came back faster than supply chains could cope. Then Russia’s invasion of Ukraine sent energy and food prices soaring. Inflation reached about 9% in the US in mid-2022 and just over 11% in the UK in October 2022, levels not seen for forty years.
Why a little inflation is considered healthy
Many central banks, including those in the US, the UK and the eurozone, aim for inflation of about 2% a year, not zero. A few reasons:
- Falling prices can be harmful. If people expect prices to fall (deflation), they may delay spending, which slows the economy and can push prices down further. Debts also get heavier in real terms. Japan struggled with this for much of the 1990s and 2000s.
- It gives room to cut interest rates in a downturn. With interest rates already at zero and no inflation, a central bank has less room to stimulate spending.
- It eases adjustments. It’s easier for real wages to adjust over time when prices are gently rising than if some wages had to be cut outright.
The 2% figure itself is more convention than science. New Zealand pioneered inflation targeting in 1990, others followed, and 2% became the shared number.
How central banks fight it
The main tool is the interest rate. When inflation runs too high, a central bank raises rates. Borrowing becomes more expensive and saving more attractive, so spending slows, and with it the pressure on prices. When inflation is too low, it cuts rates to encourage spending.
It’s a blunt tool, and it takes time, often a year or two to have its full effect. The most famous use of it was in the US around 1980, when inflation was running above 13%. The central bank chairman, Paul Volcker, pushed interest rates to around 20%. It brought inflation down sharply, at the cost of a painful recession. Central banks have tried to avoid needing such drastic medicine since, partly by convincing people that inflation will stay low, which helps make it so.
What it means for you
Savings. If your savings earn 1% while inflation is 3%, your balance rises, but what it can buy falls by about 2% a year. Economists call the gap between the number and its buying power the difference between nominal and real values.
Try it
What your savings can buy
Put $10,000 aside. It earns interest, and prices rise. Set both, and the number of years, and see what the money will buy in today’s prices.
After 20 years the balance has grown to $12,202, but in today’s prices it buys only $6,756. The number went up; what it can buy went down.
Pay. A pay rise of 4% in a year when inflation is 6% is a real pay cut of about 2%. In 2022, many workers got the biggest pay rises in years and still ended up worse off.
Try it
Who’s better off?
Ann gets a 2% pay rise in a year when prices don’t rise at all. Barbara gets a 5% pay rise in a year when prices rise 4%. Who’s better off in what their pay can buy?
Pick one. You’ll see why straight after.
The trap here has a name: money illusion. In a well-known study, the economists Eldar Shafir, Peter Diamond and Amos Tversky gave people exactly the scenario above and found that most thought the person with the bigger number would feel happier, even when they could see the other was better off. We’re wired to notice the number on the payslip, not what it buys.
Debts. Inflation can help borrowers on fixed rates. If you owe a fixed amount and prices and wages rise, the debt shrinks in real terms. A mortgage taken out decades ago can feel small today for exactly that reason. It works the other way for lenders, and for savers.
Fixed incomes. People living on pensions or benefits that don’t rise with prices are hit hardest, which is why many pensions are linked to inflation by law. A pension of the same number of pounds or dollars for twenty years, at 3% inflation, ends up buying only about half as much as it did at the start.
A useful habit
When you compare money across time, adjust for inflation. A house that cost $50,000 in 1985 and $300,000 today hasn’t risen six-fold in real terms, because prices in general have roughly tripled over that time. When someone says wages, savings or prices have “risen”, ask: by more or less than inflation?
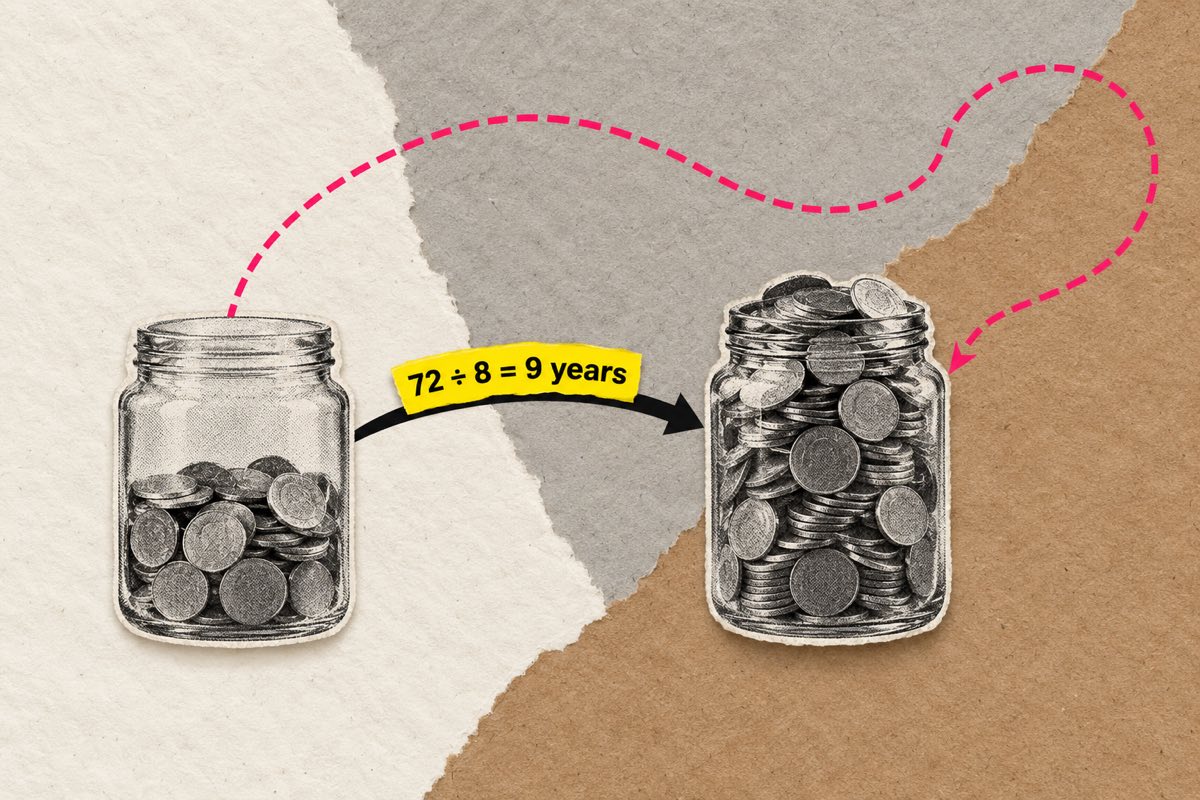
The rule of 72 helps here too: divide 72 by the inflation rate to see how long it takes prices to double. At 3%, about 24 years. At 7%, about ten.
Test yourself
The free economics test and money test both have questions on inflation, including the difference between falling inflation and falling prices. This article is general education about how inflation works, not financial advice.
Questions people ask
- What is inflation in simple terms?
- A general rise in prices over time. If inflation is 3% a year, a basket of things that cost $100 last year costs about $103 now. Another way to see it is that each dollar or pound buys a little less each year.
- What causes inflation?
- Usually some mix of demand outrunning what the economy can produce, rising costs such as energy, people expecting prices to rise and acting on it, and money growing faster than the supply of goods. The 2021 to 2023 surge combined supply problems after the pandemic, an energy shock and strong demand.
- Why do central banks want 2% inflation instead of zero?
- Because falling prices can be harmful: people may delay spending, debts get heavier and economies can stall. A little inflation gives room to cut interest rates in a downturn and makes it easier for wages and prices to adjust. Two per cent is a convention many central banks share.
- How does inflation affect my savings?
- If your savings earn less interest than the inflation rate, their buying power shrinks even as the balance grows. At 3% inflation and 1% interest, savings lose about 2% of their buying power each year, roughly a third over 20 years.
- Does inflation falling mean prices are falling?
- No. Falling inflation means prices are rising more slowly. If inflation drops from 8% to 3%, prices are still going up, just less quickly. For prices to actually fall you’d need deflation, a negative inflation rate.
Sources and further reading
- Office for National Statistics. Consumer price inflation, UK (CPI).
- US Bureau of Labor Statistics. Consumer Price Index.
- Bank of England. What is inflation? (Knowledge Bank).
- Shafir, E., Diamond, P. and Tversky, A. (1997). Money illusion. Quarterly Journal of Economics, 112(2), 341–374.
- Fergusson, A. (1975). When Money Dies: The Nightmare of the Weimar Collapse. William Kimber.
- Hanke, S. H. and Kwok, A. K. F. (2009). On the measurement of Zimbabwe’s hyperinflation. Cato Journal, 29(2), 353–364.