Compound Interest Explained: Why Growth Speeds Up
Why $1,000 at 10% a year becomes over $17,000 in 30 years, not $4,000. How compounding works, why starting early wins, and how it works against you in debt.
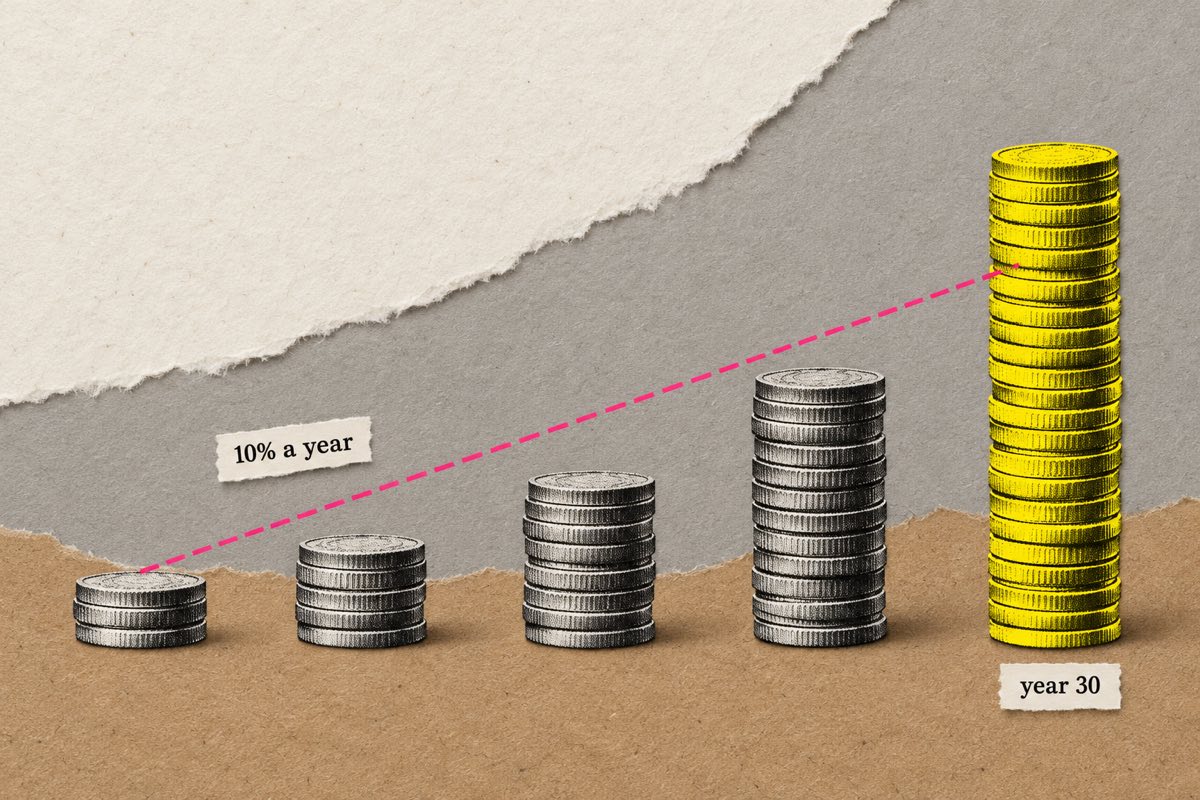
Put $1,000 somewhere that grows 10% a year. After one year you have $1,100: $100 more. How much will you have after 30 years?
Most people reason in a straight line. $100 a year for 30 years is $3,000, so about $4,000 in total. The real answer is about $17,449: more than four times as much. The difference is compounding, and it is one of the most useful ideas in personal finance, mostly because it works so quietly that people underrate it until it’s too late to use.
Try it
Simple against compound growth
$1,000, growing each year. Change the rate and the time.
After 30 years, simple growth gives $4,000. Compound growth gives $17,449: 4.4 times as much, all of it growth earned on earlier growth.
Interest on your interest
In the first year, you earn 10% of $1,000: $100. In the second year, you earn 10% of $1,100: $110. In the third, 10% of $1,210: $121.
Each year’s growth is added to the pile, and next year’s growth is worked out on the bigger pile. The amount you add keeps growing, and by year 30, a single year adds about $1,600, sixteen times the first year’s $100. The toy at the top shows the two lines side by side: simple growth, where you add the same $100 every year, and compound growth, where the line bends upwards.
| Year | Simple growth (10% of $1,000) | Compound growth (10% of the total) |
|---|---|---|
| 1 | $1,100 | $1,100 |
| 5 | $1,500 | $1,611 |
| 10 | $2,000 | $2,594 |
| 20 | $3,000 | $6,727 |
| 30 | $4,000 | $17,449 |
For the first few years the two barely differ. That’s the trap. Compounding is invisible early on and enormous later, so people who look at the first five years conclude it doesn’t matter much. By the time the curve is obviously steep, the years that made it steep have already gone, and you can’t buy them back.
Why it surprises us
Our intuition is linear: we picture adding the same amount each time. That works for short periods and small rates, which is where most of our everyday experience comes from. Over long periods, compounding pulls away from the straight line, slowly at first and then fast.
The same blind spot shows up with anything that grows by a percentage: populations, viruses, the spread of an idea online, prices. A famous puzzle makes the point. A pond has a lily that doubles in size each day, and it takes 48 days to cover the pond. How long to cover half? Not 24 days, but 47. The last doubling does half the work.
Time beats almost everything
The most powerful variable in compounding isn’t the rate, it’s time. Here is the classic illustration.
Try it
Start early, or save more?
Two savers put in $100 a month and earn the same return. Ana starts at 25 and stops after ten years. Ben starts at 35 and keeps going until 65. Change the return and see who ends up ahead.
At 7.0% a year, Ana ends with about $126,209 and Ben with about $113,353, though Ben paid in three times as much. Ana’s money had thirty extra years to earn returns on its returns.
At 7% a year, someone who saves $100 a month from 25 to 35 and then stops, leaving the money alone, ends up with more at 65 than someone who starts at 35 and saves $100 a month for thirty years, even though the second person paid in three times as much. The early saver’s money had thirty extra years in which its returns earned returns.
That doesn’t mean it’s too late to start at 40, or 50. It means the best time to start is earlier than you think, and that small amounts saved early can beat larger amounts saved later.
Two ways compounding works against you
Debt
The same maths runs in reverse. Credit card interest left unpaid is added to what you owe, and then charged interest itself. At 22% a year, an unpaid balance roughly doubles in just over three years. Paying only the minimum each month can mean a debt takes many years to clear and costs more than the original amount borrowed.
That’s why clearing expensive debt usually comes before saving: paying off a card charging 22% is like earning a guaranteed 22% return, which no savings account offers.
Fees and inflation
Investment fees look tiny: 1% a year, 0.5% a year. But a fee is a negative return, and it compounds too.
Try it
What a 1% fee really costs
Invest $10,000 for decades. One fund charges a small yearly fee, another charges more. The difference looks tiny each year. Slide it.
After 30 years, the extra 1.0% a year has cost 25% of your final pot: $76,123 against $57,435. A fee is a negative return that compounds too.
Over 30 years at 7%, an extra 1% a year in fees costs about a quarter of your final pot. Inflation does something similar to cash: at 3% a year, prices double in about 24 years, so money that earns nothing loses half its buying power in that time. There’s more on that in what inflation does to your money.
How often does it compound?
Interest can be added yearly, monthly or even daily. The more often it’s added, the sooner each bit of interest starts earning its own interest, so the effective yearly rate is a little higher than the headline rate.
A loan charging 1% a month sounds like 12% a year. Compounded monthly, it’s about 12.7%. A loan charging 2% a month is about 27% a year, not 24%. That’s why lenders quote an APR and savers look for the AER or APY: these figures convert everything to a yearly rate so you can compare like with like.
The rule of 72
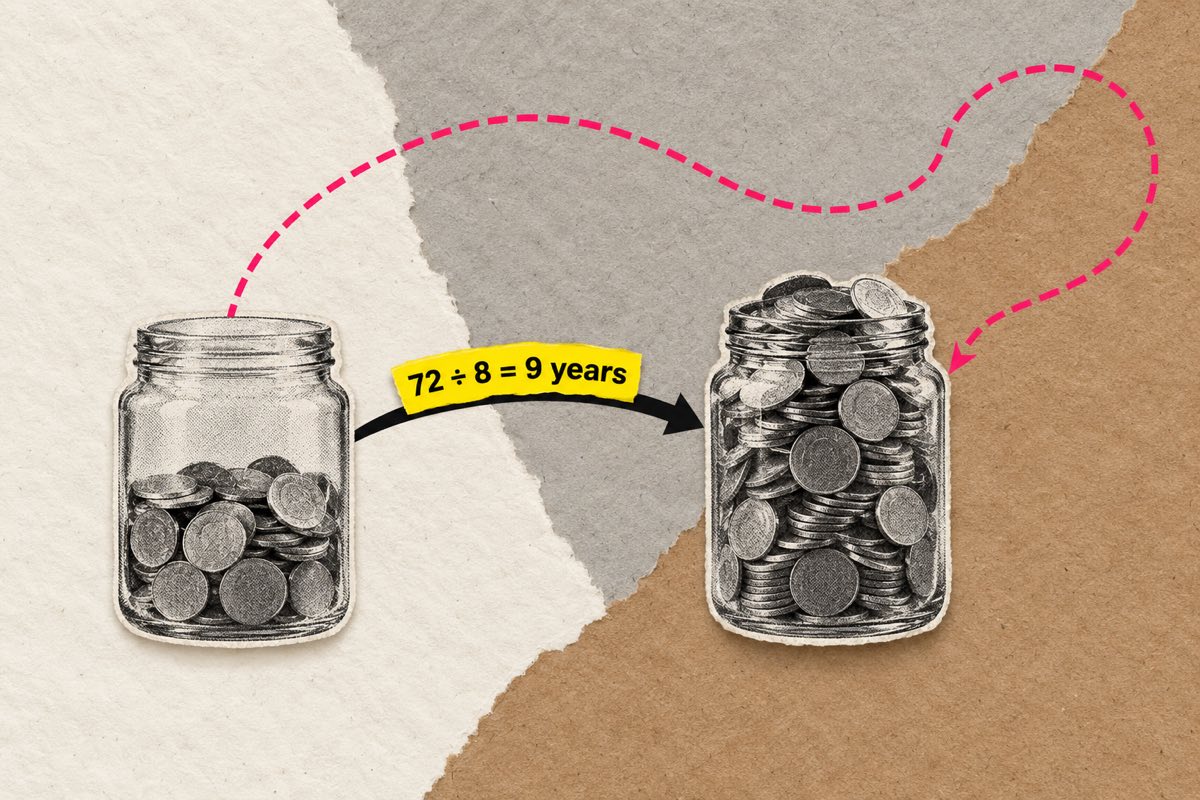
There’s a shortcut for how long money takes to double: divide 72 by the yearly rate. At 6%, money doubles in about 12 years; at 9%, about 8. It’s a quick way to feel how much a rate matters over time. The rule of 72 article shows where it comes from, and when it stops working.
A bet across two centuries
When Benjamin Franklin died in 1790, he left £1,000 each to the cities of Boston and Philadelphia, to be lent to young tradesmen at 5% interest, with instructions that the funds be left to grow for two hundred years. He even did the sums, predicting what the money would be worth.
Things didn’t go entirely to plan; loans went unpaid and rules changed. But when the funds were finally wound up around 1990, they were worth several million dollars between them. Franklin understood something many people still don’t: the main ingredient in compounding isn’t cleverness. It’s patience.
The quote that isn’t
You’ll often read that Albert Einstein called compound interest “the eighth wonder of the world” or “the most powerful force in the universe”. There’s no evidence he said either. Quotation researchers have found no source from his lifetime, and the line appears to have been attached to him decades after his death because it sounds better coming from a genius. The idea is sound. The attribution isn’t.
It isn’t only money
Compounding describes anything where the gain each period depends on what you already have. Knowledge works like this: each idea you understand makes the next related one easier to learn, so people who keep learning in a field pull away from those who stopped, slowly at first and then fast. Skills, savings habits, reputations and networks compound too.
So do the bad versions. A small daily habit that costs you a little attention, money or health is a negative rate, and over years it adds up the same way. The arithmetic doesn’t care what’s compounding. It only rewards whatever you keep doing for longest, which is a useful thing to know about your own life as well as your savings.
What to do with this
- Start early, even small. Time does more work than the amount.
- Leave it alone. Withdrawing returns stops them compounding.
- Watch the fees. A small yearly fee compounds into a big loss.
- Clear expensive debt first. Compounding against you at 22% beats compounding for you at 5%.
- Think in doubling times. At 7%, about ten years; at 3%, about 24.
All of this is general education about how the maths works, not advice for your own situation. Returns on investments aren’t steady or guaranteed, and for decisions about your own money it’s worth talking to a qualified adviser.
If you’d like to test your money instincts, the free money test covers compounding, tax brackets, fees and the traps around them.
Questions people ask
- What is compound interest in simple terms?
- Interest on your interest. Each period you earn a return on the money you started with and on all the returns you’ve already earned, so the amount added grows every year. Over long periods this makes growth accelerate dramatically compared with simple interest.
- What’s the difference between simple and compound interest?
- Simple interest is paid only on the original amount, so it adds the same sum each year: $1,000 at 10% gains $100 a year forever. Compound interest is paid on the growing total, so the second year adds $110, the third $121, and so on. After 30 years the gap is enormous.
- How much will $1,000 grow in 30 years?
- It depends on the rate. At 5% a year it becomes about $4,300; at 7%, about $7,600; at 10%, about $17,400. Returns on investments aren’t steady or guaranteed, so treat these as illustrations of the maths, not forecasts.
- Did Einstein call compound interest the eighth wonder of the world?
- There’s no evidence he did. The quote is attributed to him all over the internet, but no source from his lifetime has ever been found, and quotation researchers consider it a misattribution. The idea behind it is still sound.
- How does compound interest affect debt?
- The same way, in reverse. Unpaid interest is added to what you owe and then charged interest itself. At 22% a year, a debt left alone roughly doubles in a little over three years, which is why expensive debt is usually worth clearing before saving at a lower rate.
Sources and further reading
- Financial Conduct Authority. MoneyHelper: How compound interest works.
- US Securities and Exchange Commission, Investor.gov. Compound interest calculator and explanation.
- Bogle, J. C. (2007). The Little Book of Common Sense Investing. Wiley. (On the compounding cost of fees.)
- O’Toole, G. (2011). Compound interest is the most powerful force in the universe. Quote Investigator.
- Franklin, B. (1789). Codicil to his last will and testament (the Boston and Philadelphia bequests).